
How to invoice a brand collaboration in Spain (creator guide with template)
How to invoice a brand as an influencer in Spain: the required fields, which IVA and IRPF lines apply by where the brand is, product deals, and a free template.
To invoice a brand as an influencer in Spain, you issue a full invoice (factura completa) from your own numbered series with both parties' legal names, tax IDs and addresses, a description of the deliverables, the taxable base, the IVA line and, when a Spanish business pays you, the IRPF withholding line. The IVA and IRPF lines change with where the brand is established and how you are registered, so check those two lines every time.
Picture a food creator in Seville who just finished two reels for a restaurant group in Madrid. The posts are live, the brand's finance team asks for "la factura", and she has never written one. This guide is for that moment. It is the creator-side mirror of our influencer invoice checklist for brands: the same rules, seen from the person who sends the invoice. It covers the fields, a template you can copy, the IVA and IRPF lines by payer location, collaborations paid in product, a worked example, and what to ask your gestor.
It is general information, not tax advice. Secondary sources disagree on several points below, especially how influencers are classified and how product deals are taxed. Where they disagree, this guide says so, cites the official text, and tells you to confirm with your gestor or tax adviser. If you have not yet agreed the deal itself, start with the creator's guide to brand deals, which covers pricing, contracts and payment terms.
What must your invoice to a brand include?
A full invoice must include every field in article 6.1 of Real Decreto 1619/2012, the Spanish invoicing regulation, that applies to the operation. A business customer needs a full invoice to support the expense and deduct the IVA, so do not send a simplified ticket. The figure marks the eight fields a brand's finance team checks first; the table below lists all twelve lines.
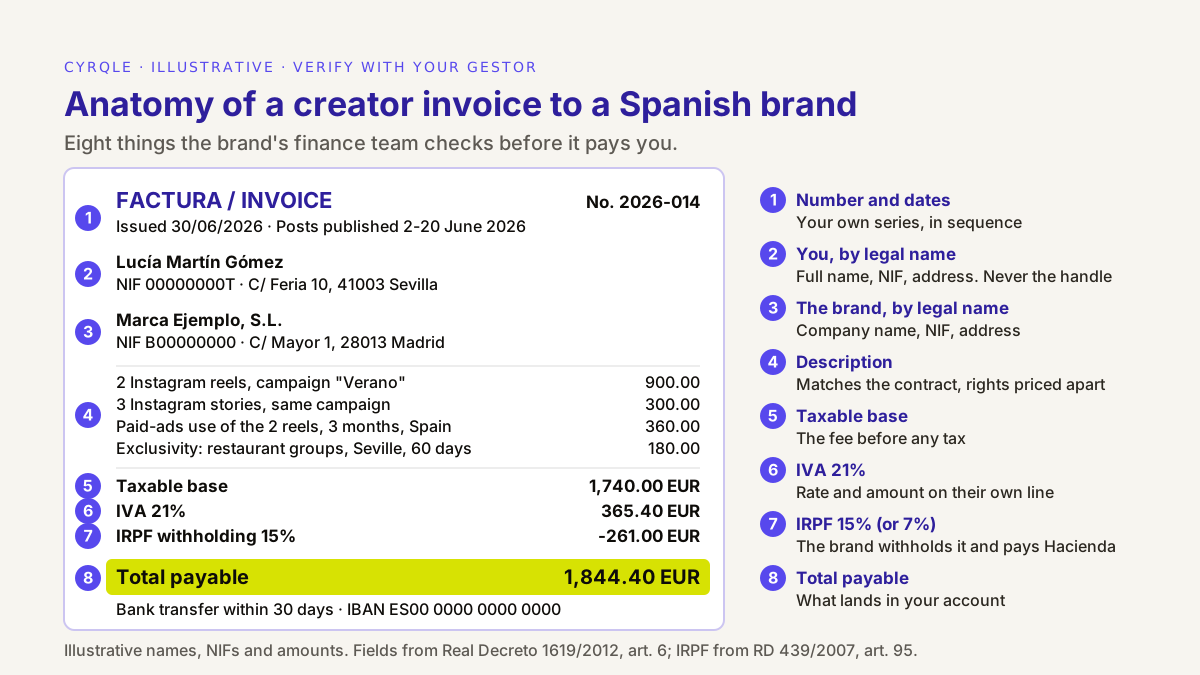
| # | Field | Article of RD 1619/2012 | What to write |
|---|---|---|---|
| 1 | Number and series | 6.1.a | A number in your own series, in sequence with no gaps (for example 2026-014). |
| 2 | Issue date | 6.1.b | The date you issue the invoice. |
| 3 | Date of the operation | 6.1.i | Add it when it differs from the issue date, for example posts published in May and invoiced in June. |
| 4 | Your full legal name | 6.1.c | Name and both surnames, or your company's registered name. Never your handle. |
| 5 | Both tax IDs | 6.1.d | Your NIF and the brand's NIF. For an EU brand, its VAT number, and your NIF-IVA (your NIF with the ES prefix). |
| 6 | Both addresses | 6.1.e | Your tax address and the brand's registered address. |
| 7 | Description | 6.1.f | Deliverables, platform, campaign and period. If usage rights or exclusivity have their own price, put them on their own line. |
| 8 | Taxable base | 6.1.f and 6.1.h | Your fee before tax, per line and in total. |
| 9 | IVA rate and amount | 6.1.g and 6.1.h | 21% for most services to a Spanish business, shown on its own line. |
| 10 | Note when there is no Spanish IVA | 6.1.m for EU brands | "Inversión del sujeto pasivo" (reverse charge) for an EU business. For a non-EU business article 6 requires no wording, but add the legal reason (non-subject, article 69) so the brand's finance team does not ask. |
| 11 | IRPF withholding | Not in article 6 | The rate and the amount the Spanish brand withholds. Not a legal field of the invoice, but finance expects it. |
| 12 | Total payable | Not in article 6 | Base + IVA − IRPF. This is the amount that should reach your account. |
Three rules sit around the fields:
- Deadline. When the customer is a business, you must issue the invoice before the 16th day of the month after the month the IVA fell due (article 11). For a campaign delivered in June, invoice by 15 July at the latest.
- Language and currency. Any language and any currency are allowed (article 12). For a foreign brand, a bilingual invoice in Spanish and English works well.
- Corrections. You never edit a sent invoice. You issue a corrective invoice (factura rectificativa) that refers to the original (article 15).
A template you can copy
Copy this into your invoicing software or a document, then replace every field in square brackets. It is set up for the most common case: a Spanish creator registered as a professional autónomo, invoicing a Spanish business. The next sections tell you which lines to change for other payers.
FACTURA / INVOICE                                 No. [2026-014]
Fecha de expedición / Issue date:                  [30/06/2026]
Fecha de la operación / Date of service:           [2-20 June 2026]

EMISOR / FROM
[Your full legal name]
NIF: [your NIF]
[Your tax address, postcode, city]

CLIENTE / BILL TO
[Brand's registered company name]
NIF / VAT number: [brand's NIF or EU VAT number]
[Brand's registered address]

CONCEPTO / DESCRIPTION                                   EUR
[2 Instagram reels, campaign "...", published ...]   [900.00]
[3 Instagram stories, same campaign]                 [300.00]
[Paid-ads use of the reels, 3 months, Spain]         [360.00]
[Exclusivity: category, territory, days]             [180.00]

Base imponible / Taxable base                      [1,740.00]
IVA 21%                                              [365.40]
Retención IRPF 15% / IRPF withholding               [-261.00]
TOTAL A PAGAR / TOTAL PAYABLE                      [1,844.40]

Forma de pago / Payment: bank transfer within [30] days
IBAN: [your IBAN, in your name]
Contract / PO reference: [the brand's reference, if any]
[Note line: reverse-charge or non-subject wording, when it applies]
Two habits save most back-and-forth. Ask the brand for its exact billing data (registered name, NIF, address, any purchase order number) when you sign the contract, not when you invoice. And make the description match the contract word for word: if the contract says "two reels and three stories", the invoice should too. Our influencer contract template for Spain has a fee and invoice clause that sets this data out in advance.
Which IVA line applies? It depends on where the brand is
For a service from one business to another, IVA is charged where the customer is established, not where the audience is or where you film (Ley 37/1992 on IVA, article 69). This guide assumes you are resident in mainland Spain or the Balearic Islands; the Canary Islands, Ceuta and Melilla have their own indirect taxes (IGIC and IPSI), so ask your gestor.
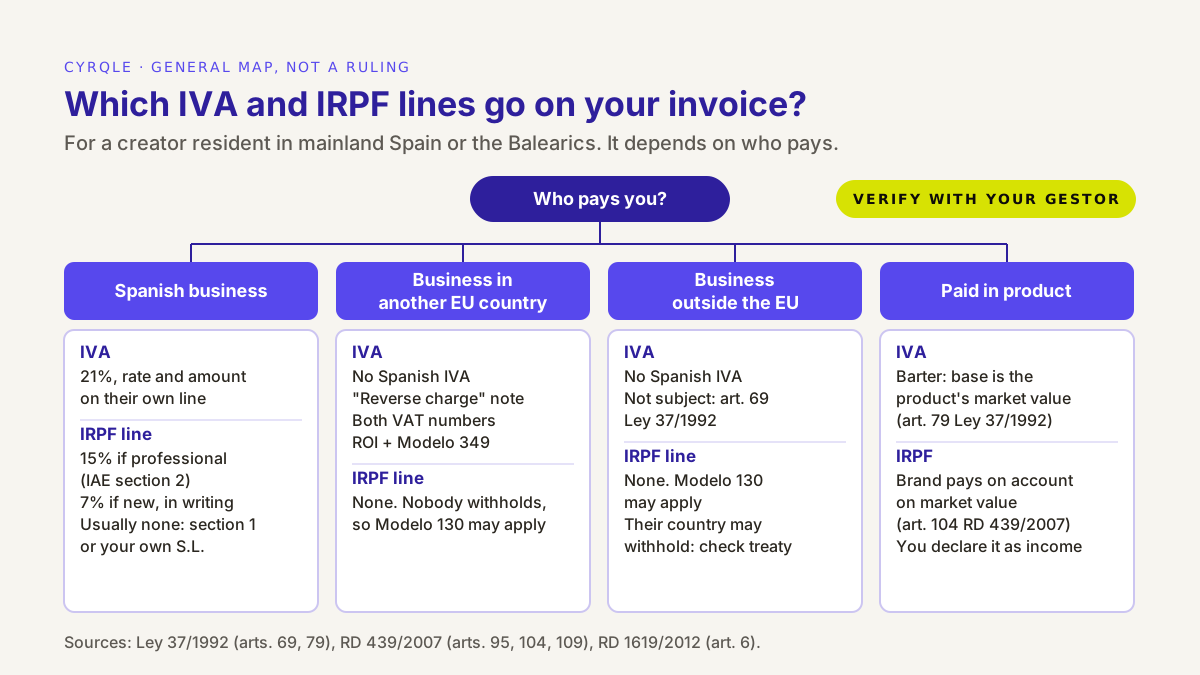
| IVA line | IRPF line | Extra steps for you | |
|---|---|---|---|
| Business established in Spain | 21%, rate and amount shown | 15%, or 7% with a written notice; usually none for a business activity or your own S.L. | Declare the IVA charged in Modelo 303 |
| Business in another EU country | No Spanish IVA; note 'Inversión del sujeto pasivo / Reverse charge' | None | NIF-IVA and ROI registration; Modelo 349; Modelo 130 may apply |
| Business outside the EU | No Spanish IVA; note that the service is not subject (article 69 Ley 37/1992) | None from Spain; the brand's country may have its own rules | Modelo 130 may apply; ask about any foreign withholding and treaty relief |
| Payment in product | Barter: base is the product's market value (article 79) | The brand makes a payment on account on the value | Agree the paperwork with your gestor first |
A brand established in Spain
Charge 21% IVA, the general rate (Agencia Tributaria), and show the rate and amount on their own line. The IVA is not your income. You collect it for Hacienda and declare it in your quarterly Modelo 303, minus the IVA on your own deductible expenses.
A brand in another EU country
Do not charge Spanish IVA. The service is located in the brand's country, and the brand accounts for the VAT there under the reverse charge. Your invoice shows no IVA, both VAT numbers, and the note "Inversión del sujeto pasivo" or "Reverse charge" (article 6.1.m of the invoicing regulation; article 226 of Directive 2006/112/EC).
Two steps people miss:
- Register in the ROI before the first invoice. The Agencia Tributaria says a business established in Spain must obtain a NIF-IVA and register in the Registro de Operadores Intracomunitarios when it provides services located in another member state where the customer is liable for the tax (AEAT: ROI, VIES and NIF-IVA). You apply on Modelo 036. Then report these invoices in Modelo 349.
- Check the brand's VAT number in the EU's VIES system before you send the invoice. If the brand has no valid VAT number, it may not be acting as a business, and the treatment changes. Ask your gestor.
A brand outside the EU
For a business customer established outside the EU, for example in Mexico, the United Kingdom or the United States, the service is not located in Spain (article 69.Uno.1º), so you do not charge Spanish IVA. You still issue an invoice under the Spanish rules, because you are established in Spain (article 2.3 of the invoicing regulation). A common wording is "Operación no sujeta a IVA por reglas de localización (art. 69 Ley 37/1992)"; your gestor may prefer another.
This is a point where older guides conflict with the current law. Some describe a "use and enjoyment" rule that taxed advertising services in Spain when they were used in Spain. The current text of article 70.Dos limits that rule to customers who are not businesses. If the brand is a business, the general rule applies. Ask your gestor to confirm before your first non-EU invoice.
When does the brand withhold IRPF from your invoice?
A Spanish business that pays you for a professional activity must withhold IRPF from your fee and pay it to Hacienda on your behalf (Real Decreto 439/2007, articles 76 and 95). The withheld amount is not lost: it is an advance on your income tax, and you deduct it in your annual return.
The rate depends on your situation:
- 15% is the general rate for professional income (article 95.1).
- 7% applies in the year you start a professional activity and the two years after, if you did not work as a professional in the year before you started. You must tell the brand in writing, and the brand keeps your signed notice.
- 7% under a second rule. The same article also lists group 869 of section 2 of the IAE for a 7% rate when, in the previous year, your income from those activities was under 15,000 euros and more than 75% of your total income from work and activities. Group 869 is the heading the tax authority used for an influencer in ruling V2390-24. If you think this applies, ask your gestor and give the brand the written notice the article requires.
- Usually no withholding if your activity is registered as a business (section 1 of the IAE) or if you invoice through your own company. Image-rights licences follow their own withholding rules, so ask before you split a fee into "services" and "image rights".
Whether a content creator is a professional (section 2) or a business (section 1) is where sources conflict most. The Dirección General de Tributos placed a content creator in section 1 headings for video and photography in ruling V0773-22 (2022), and in group 869 of section 2 in ruling V2390-24 (2024). Both rulings are in the DGT rulings database. Your heading is on your census registration (Modelo 036 or 037). Tell the brand which heading you have, and let your gestor decide which one fits your work. The full brand-side reasoning is in our guide to IRPF and IVA on influencer payments.
Foreign brands do not withhold, so you may owe Modelo 130
A brand with no establishment in Spain does not withhold Spanish IRPF. Nothing is wrong with that invoice, but nobody is paying tax on account for you. That brings in the quarterly payment on account, Modelo 130: in direct assessment, 20% of your net income for the year to date, minus earlier payments and withholdings (article 110).
Professionals are exempt from Modelo 130 if at least 70% of their activity income in the previous year was subject to withholding or a payment on account (article 109.2). A creator paid mostly by Spanish brands often meets that test. A creator who moves to mostly foreign brands can lose it. Check the ratio with your gestor every January.
How do you invoice a collaboration paid in product?
A collaboration paid only in product is not tax-free just because no money moved. If you are a professional creator, the product is payment in kind for your service. Two rules apply, and sources disagree on the paperwork:
- IVA. When the payment is not money, the taxable base is its value in money (Ley 37/1992, article 79). In practice, you invoice your service at the product's market value and charge IVA on it, and the brand may owe IVA on the product it handed over. Who pays the IVA amount in cash, and how, is something to agree with the brand and your gestor in advance.
- IRPF. A Spanish brand that pays a professional in kind must make a payment on account (ingreso a cuenta) on the product's market value at the withholding rate (Real Decreto 439/2007, article 104). With a 300-euro product and a 15% rate, that is 45 euros the brand pays to Hacienda. You declare the product's value as income in your return.
For people who review products as ordinary consumers, without an economic activity, the DGT has treated products received as a capital gain in kind instead (rulings V1161-25 and V1285-25). If you invoice other brands and have an IAE registration, assume you are a professional. Our usage rights pricing calculator helps you compare a product offer with what the same work is worth in cash.
Worked example: one fee, five invoices
The same 1,000-euro fee for two reels looks different depending on who pays and how you are registered. You are a creator in Valencia, registered in a professional activity. All figures are illustrative.
| Spanish brand, 15% | Spanish brand, 7% (new) | Brand in France | Brand in Mexico | Your own S.L., Spanish brand | |
|---|---|---|---|---|---|
| Taxable base | 1,000 EUR | 1,000 EUR | 1,000 EUR | 1,000 EUR | 1,000 EUR |
| IVA line | +210 EUR | +210 EUR | 0, reverse charge | 0, not subject | +210 EUR |
| IRPF line | −150 EUR | −70 EUR | none | none | none |
| Lands in your account | 1,060 EUR | 1,140 EUR | 1,000 EUR | 1,000 EUR | 1,210 EUR |
| IVA you pass to Hacienda (Modelo 303) | 210 EUR | 210 EUR | 0 | 0 | 210 EUR |
| Income tax already paid for you | 150 EUR | 70 EUR | 0 | 0 | 0 (company pays corporate tax) |
| Extra admin | none | signed 7% notice | ROI, Modelo 349 | non-subject note | company books |
Three lessons from the table:
- The biggest transfer is not your biggest income. The 1,210 euros into your S.L. includes 210 euros of IVA that is not yours. In every Spanish column, 210 euros is Hacienda's money until you file the Modelo 303.
- Foreign invoices look larger and are not. The 1,000 euros from France or Mexico has had no tax taken off. Set part of it aside until your gestor tells you what you owe, and check whether you now need to file Modelo 130.
- The total payable must match the transfer. If the Spanish brand transfers 1,060 euros and your invoice says 1,210, one of you made a mistake on the IRPF line. Fix it with a corrective invoice, not with a new invoice under the same number.
Before you set the fee in the first place, see how much to charge for a sponsored post. Quote "before tax" so IVA is added on top, not taken out of your fee.
When to send the invoice, and what if the brand pays late?
Send the invoice when the deliverables are accepted, or on the date your contract sets, and in any case within the article 11 deadline. In Spain, when the contract sets no date, a business must pay within 30 days of receiving the service, and the parties cannot agree more than 60 days (Ley 3/2004, article 4). Put the payment term on the invoice so nobody has to look it up.
If something on a sent invoice is wrong (an IRPF rate, a missing NIF, a wrong amount), issue a corrective invoice that cites the original's number and date and shows the right figures. Keep both.
From 2027, invoicing software must meet the Verifactu requirements of Real Decreto 1007/2023. Real Decreto-ley 15/2025 set 1 July 2027 as the date for autónomos. If you use software to invoice, check that your provider will be compliant by then. The fields in this guide do not change.
Questions to take to your gestor
Ask these once, at the start of the year or when your work changes, and keep the answers:
- Is my activity professional (section 2, for example group 869) or business (section 1), and which IRPF rate should brands apply?
- Do I qualify for the 7% rate, under either rule in article 95.1, and what notice do I give brands?
- Do I need to register in the ROI before my first invoice to an EU brand?
- What wording do you want on invoices to non-EU brands, and how do I handle a foreign brand that withholds tax in its own country?
- How do we document collaborations paid in product, or part cash and part product?
- Do I need to file Modelo 130 this year, given how much of my income was withheld last year?
How cyrqle helps
cyrqle is a creator commerce platform where brands run campaigns and pay creators. On the creator side, you connect Instagram and TikTok, receive briefs, sign the contract in the app and follow your payouts. It does not write or send your tax invoice, decide your IVA or IRPF treatment, collect tax forms or file returns. That stays with you and your gestor.
What it does give you is a clean record to invoice against:
- The terms are fixed before you start. A brand cannot invite you until it has set the compensation: Cash payment, Commission on every sale, Product gift, or a combination. You and the brand e-sign the Creator Collaboration Agreement, and the terms are frozen at signature, so the fee on your invoice has a signed source. See compensation and contracts.
- A statement per payout. Each payout records the split: your net amount, any tax withheld, the cyrqle commission and any agency fee. There is a statement for every payout, which makes it easy to check that the transfer matches your invoice's total payable.
- Paid to your bank in euros. Creators in Europe and the US onboard to Stripe Connect and are paid to their own bank account. Settlement is in EUR. A person on the brand's side releases each payout after delivery, so the timing follows the brand's approval, not an automatic clock.
- Commission is shown, not paid automatically. For commission deals, the amount owed is calculated and shown; paying it is a separate step, with its own invoice from you.
The payout statement is a payment record, not an invoice. Keep it next to your invoice, not instead of it. cyrqle is free for creators; see cyrqle for creators to join the waitlist.
FAQ
Do I have to be an autónomo to invoice a brand in Spain?
Usually, yes, if you work with brands regularly. Issuing invoices for an economic activity means registering with Hacienda (Modelo 036 or 037) and, in most cases, as self-employed with Social Security. When a one-off collaboration counts as regular activity is a judgement your gestor should make with you.
Should my invoice include IRPF if the brand is in another country?
No. Only payers established in Spain withhold Spanish IRPF, so an invoice to a foreign brand has no IRPF line. Nobody pays tax on account for you, so you may need to file Modelo 130 each quarter and should set money aside.
Do I charge IVA to a brand in another EU country?
No, if it is a business with a valid VAT number. The invoice shows no Spanish IVA, both VAT numbers and the note "Inversión del sujeto pasivo" or "Reverse charge". You need a NIF-IVA and ROI registration first, and you report the invoice in Modelo 349.
What if the brand pays me less than my invoice says?
Ask which line differs before you do anything else. Most gaps come from the IRPF line: you invoiced without withholding and the brand withheld 15%, or the reverse. If your invoice was wrong, issue a corrective invoice. If the brand underpaid, send a polite reminder that cites the invoice number and the agreed payment term.
Can I invoice in English or in another currency?
Yes. The invoicing regulation allows any language and any currency (article 12 of Real Decreto 1619/2012). A bilingual Spanish and English invoice is a good default for foreign brands. Your gestor will tell you how to record the exchange rate for your own books.
Is a cyrqle payout statement an invoice?
No. The statement records what was paid, the split and the transfer reference. It is a payment record. You still issue your own invoice to the brand, and you keep both.
Related
- The creator's guide to brand deals: pricing, contracts and getting paid, before the invoice.
- Influencer invoice checklist for brands in Spain: what the brand's finance team checks on your invoice.
- How to pay influencers in Spain: the brand's side of IRPF, IVA and foreign creators.
Sources
- Real Decreto 1619/2012, Reglamento de facturación (articles 2, 6, 11, 12 and 15): BOE-A-2012-14696
- Real Decreto 439/2007, Reglamento del IRPF (articles 76, 95, 104, 109 and 110): BOE-A-2007-6820
- Ley 37/1992, del IVA (articles 69, 70 and 79): BOE-A-1992-28740
- Directive 2006/112/EC on the common system of VAT (article 226): EUR-Lex
- Agencia Tributaria, VAT rates and ROI, VIES and NIF-IVA
- Ley 3/2004, late payment in commercial transactions (article 4): BOE-A-2004-21830
- Real Decreto 1007/2023, invoicing software requirements: BOE-A-2023-24840
- Real Decreto-ley 15/2025, Verifactu dates: BOE-A-2025-24446
- DGT binding rulings V0773-22, V2390-24, V1161-25 and V1285-25: Dirección General de Tributos rulings database
Related material.
Influencer invoice requirements in Spain as a printable checklist: mandatory fields, IRPF and IVA lines, foreign creators, gifted product and what to file.
Free influencer media kit template, in English and Spanish: eight sections from median views to rates and usage rights, with a filled example.
A step-by-step guide to collecting customer and creator posts about your brand from Instagram and TikTok: choosing terms, picking a fetch mode, scheduling monitors with a budget cap, and reviewing the queue.